Accidental Landlord Tax: What Renting Out Your Home Actually Nets You
2026-08-25
Most landlord tax advice is written for people who chose to be landlords. It assumes a portfolio, a strategy, and an accountant. It is not much use if you inherited your mother's house, moved in with a partner and kept the flat, or took a job in another city and could not sell.
If that is you, the question is simpler and more urgent: what does renting this out actually leave me, after tax? Often less than people expect, and occasionally less than nothing.
First: Yes, You Have to Declare It
Rental income is taxable income. If your gross rental income is more than £1,000 in a tax year, you need to tell HMRC. Below £1,000 the property allowance covers you and there is nothing to do.
Above that threshold you register for Self Assessment and file a return. The deadline is 31 January following the end of the tax year — so rent received in the 2026/27 tax year is declared by 31 January 2028. Registering late carries penalties, and "I didn't know" is not a defence HMRC accepts.
This is not optional and it is not invisible HMRC receives data from letting agents, the Land Registry, tenancy deposit schemes and council tax records. The Let Property Campaign exists specifically to let unreported landlords come forward voluntarily, with lower penalties than being found.
What You Can Actually Deduct
You are taxed on profit, not on rent. Allowable expenses include:
- Letting agent and management fees
- Landlord insurance
- Repairs and maintenance (fixing what is there — not improving it)
- Ground rent and service charges
- Council tax and utilities during void periods
- Safety certificates — gas, EICR, EPC
- Accountancy fees for the property
The distinction that catches people is repair versus improvement. Replacing a broken boiler with an equivalent boiler is a repair and deductible now. Replacing a functioning kitchen with a better one is an improvement — not deductible against income, though it may reduce Capital Gains Tax when you eventually sell. Keep the receipts either way.
The Section 24 Trap
Here is the part that genuinely surprises people, and it disproportionately hits accidental landlords because they usually still have a mortgage on the property.
Until 2017 you could deduct mortgage interest as an expense. You cannot any more. Instead you get a tax credit worth 20% of the interest. For a basic-rate taxpayer this makes almost no difference. For a higher-rate taxpayer it is a significant extra cost — and worse, your full rental income counts toward your total income, which can push you into a higher band you were not in before.
Section 24 means it is possible to make a cash loss on a rental property and still owe tax on it.
The same property, two taxpayers
Gross rent £14,400 a year. Mortgage interest £9,000. Other allowable expenses £2,400.
:::stats £3,000 | Cash profit £12,000 | Taxable profit — interest NOT deducted £600 | Basic-rate tax bill £3,000 | Higher-rate tax bill :::
The basic-rate taxpayer keeps £2,400 of their £3,000. The higher-rate taxpayer keeps nothing — the tax bill equals the cash profit exactly. Same property, same rent, same mortgage.
And if the boiler goes that year, the higher-rate taxpayer is subsidising their tenant.
The Questions Worth Asking Before You Let
Does the rent actually cover the costs? Not just the mortgage — insurance, safety certificates, agent fees, and a realistic void allowance. Two weeks empty a year is normal, not pessimistic.
What band will this push me into? If you are near the higher-rate threshold, adding rental income can move you across it, and the effect is not limited to the rent.
Would selling be better? If you lived in the property as your main home, Private Residence Relief may cover much or all of the gain — but that relief tapers the longer you let it out. There can be a real cost to waiting.
What about the 2030 EPC deadline? Every privately rented home in England and Wales must reach EPC C by 1 October 2030, with landlords required to spend up to £10,000 on improvements. If the property is rated D or E, that is a cost with a date on it.
:::tool epc-calculator Check what your property is rated :::
Work Out Your Actual Number
The honest answer to "is this worth it?" is arithmetic, not opinion. You need your gross rent, your mortgage interest, your real running costs and your other income — then the Section 24 mechanics applied properly rather than guessed at.
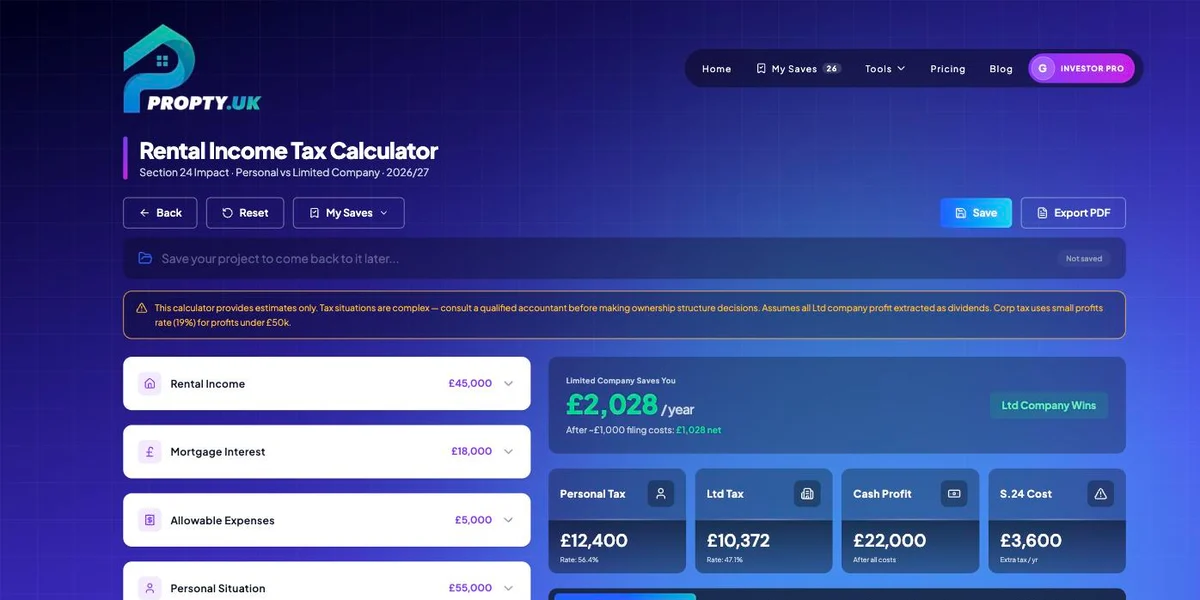
Propty's Rental Tax Calculator does exactly that: it applies the 2026/27 bands, models the Section 24 restriction as a credit rather than a deduction, and shows your cash profit alongside your tax bill so you can see the gap between them.
:::tool rental-tax Calculate what you'll actually keep :::
You did not choose to be a landlord. You can still choose to do it with the numbers in front of you.