How to Appraise Land for Development in the UK (Residual Land Value)
2026-08-25
Ask a surveyor to appraise a development site and you will get a thorough PDF in about a fortnight, for somewhere between £500 and £1,500. That is money well spent — right before you exchange. It is money badly spent on the seven sites you looked at and rejected first.
The method professionals use is called residual land value, and there is nothing secret about it. It is arithmetic. You can run it yourself in ten minutes to decide whether a site is worth a surveyor's time at all.
What Residual Land Value Actually Means
Most valuations work forwards: here is the thing, here is what similar things sold for, therefore here is the price. Land does not work that way, because a plot of land has no inherent value — its value comes entirely from what you are allowed to build on it and what that finished building will sell for.
So you work backwards. Start with what the completed development will be worth. Subtract every cost of getting there. Subtract the profit you need to justify the risk. Whatever is left is what you can afford to pay for the land.
Land value is not what the land is worth. It is what is left over after everything else has been paid for.
That "left over" figure is the residual land value. It is also, usefully, your maximum bid — pay more and you are eating into your profit margin.
The Five Inputs
1. Gross Development Value (GDV)
GDV is the total sales revenue from the finished scheme. Four houses at £320,000 each gives a GDV of £1,280,000.
Get this from comparable evidence — actual recent sale prices for equivalent finished properties in the same postcode, not asking prices and not the agent's optimism. GDV is the single biggest number in the appraisal, so an error here swamps everything else. A 10% GDV error on a £1.28m scheme is £128,000, which is often the entire profit margin.
The most common appraisal mistake Using asking prices rather than sold prices for GDV. Asking prices in a soft market can sit 5–10% above achievable values, and that gap comes straight out of your profit — or straight onto your land bid.
2. Build Costs
UK build costs in 2026 typically run £130–£180 per square foot for standard new-build housing, depending on region, specification and scheme size. High-specification or London schemes routinely exceed £200/sqft. BCIS publishes regional benchmarks; use them as a sanity check on any builder's estimate.
Build cost is where optimism is most expensive. If your appraisal only works at £130/sqft and the tender comes back at £155, you have not lost 19% of your build budget — you have lost the difference multiplied by the whole floor area, and it comes entirely out of profit.
3. Professional Fees and Finance
Architects, planning consultants, structural engineers, building control, warranty, legal fees on acquisition and sale, agent fees on disposal. As a rule of thumb these come to 10–15% of build cost, though complex or contested planning pushes it higher.
Finance is separate and often underestimated. Development finance is drawn down in stages and charged on the drawn balance, but you also pay arrangement fees, exit fees and interest through any void between practical completion and final sale.
4. CIL and Section 106
The Community Infrastructure Levy is a fixed charge per square metre set by each local authority. Section 106 agreements are negotiated site by site and can include affordable housing contributions, highways works or open-space payments.
Both reduce your land bid pound for pound, and both are easy to discover early — CIL rates are published by the council. Finding a £40,000 S106 obligation after you have agreed a price is a bad day.
5. Profit Margin
Most UK developers target 15–20% profit on GDV for speculative residential schemes. Lenders typically require a minimum of 20% for development finance, which in practice sets the floor whether you like it or not.
This is not greed — it is the buffer that absorbs a build overrun, a planning delay or a softening market. A scheme appraised at 10% margin has almost no tolerance for anything going wrong, and something usually does.
A Worked Example
A site with outline consent for four three-bed houses, 1,100 sqft each.
:::stats £1,280,000 | GDV — 4 × £320,000 £660,000 | Build — 4,400 sqft at £150 £132,000 | Fees & Finance £38,000 | CIL & S106 £256,000 | Profit at 20% of GDV £194,000 | Residual Land Value :::
£1,280,000 minus £660,000 minus £132,000 minus £38,000 minus £256,000 leaves £194,000. That is what the land is worth to you.
If the vendor wants £250,000, the deal does not work at a 20% margin — it works at roughly 15.6%, which your lender may well reject. You either negotiate, find a scheme with a higher GDV, or walk.
Where Appraisals Go Wrong
Testing only one scenario. A single set of inputs tells you what happens if everything goes to plan. Run the appraisal again with build costs up 10% and GDV down 5% — that is not pessimism, it is a normal year. If the deal still clears your margin, it is genuinely robust.
Forgetting the sale costs. Agent fees at 1–1.5% of GDV plus legals on each unit is a real number that has to sit inside the appraisal, not outside it.
Assuming the consent you want. Appraising four units on a site with outline consent for three is not an appraisal, it is a hope. Value what is consented; treat any uplift as upside.
Ignoring the timeline. Finance costs scale with time. A scheme that takes 18 months instead of 12 does not just delay your profit — it consumes a chunk of it in interest.
Run It Before You Call a Surveyor
The point of doing this yourself is not to replace professional advice. It is to make sure you only pay for professional advice on sites that survive first contact with the arithmetic.
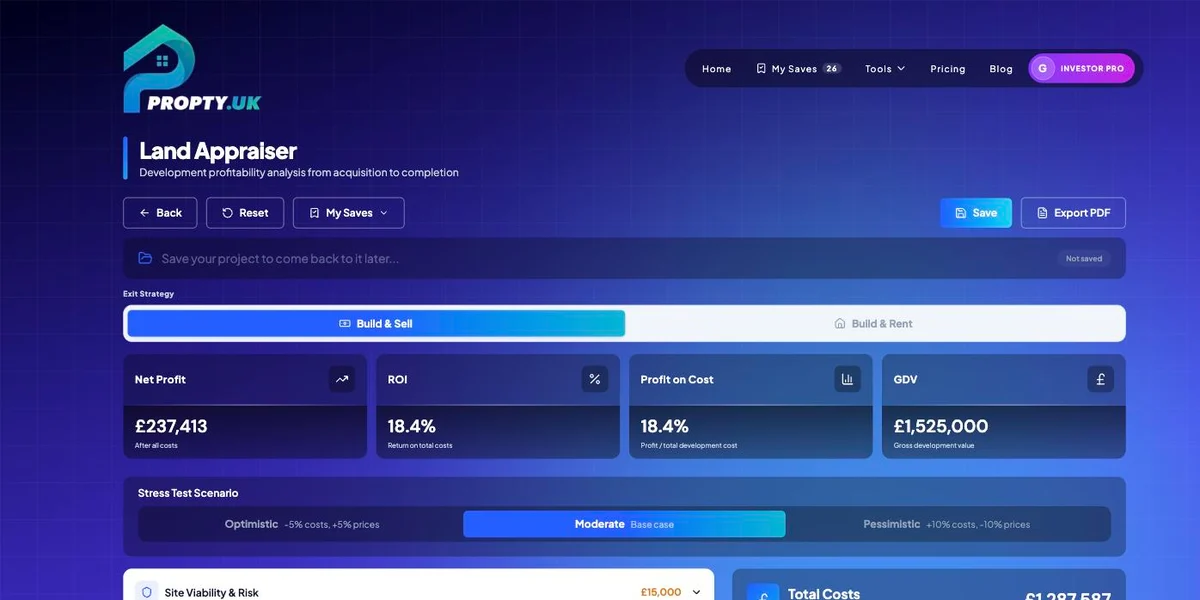
Propty's Land Appraiser runs the full residual calculation — GDV, build costs, fees, finance, CIL and S106, profit margin — and shows both the residual land value and your maximum bid. You can test what happens when build costs rise or GDV softens, and see instantly whether the deal still stands up.
:::tool land-appraiser Appraise a site in 5 minutes :::
Ten minutes of arithmetic before you commit to a fortnight of due diligence is the cheapest risk management in development.